Buying your first home in Toronto or the GTA can feel overwhelming. Between the down payment, closing costs, land transfer tax, mortgage qualification and monthly carrying costs, there is a lot to consider.
The good news is that first-time home buyers in Ontario have access to several government programs and tax incentives that can help reduce the cost of buying a home.
Some of these programs can be combined, while others apply only to specific types of properties or buyers.
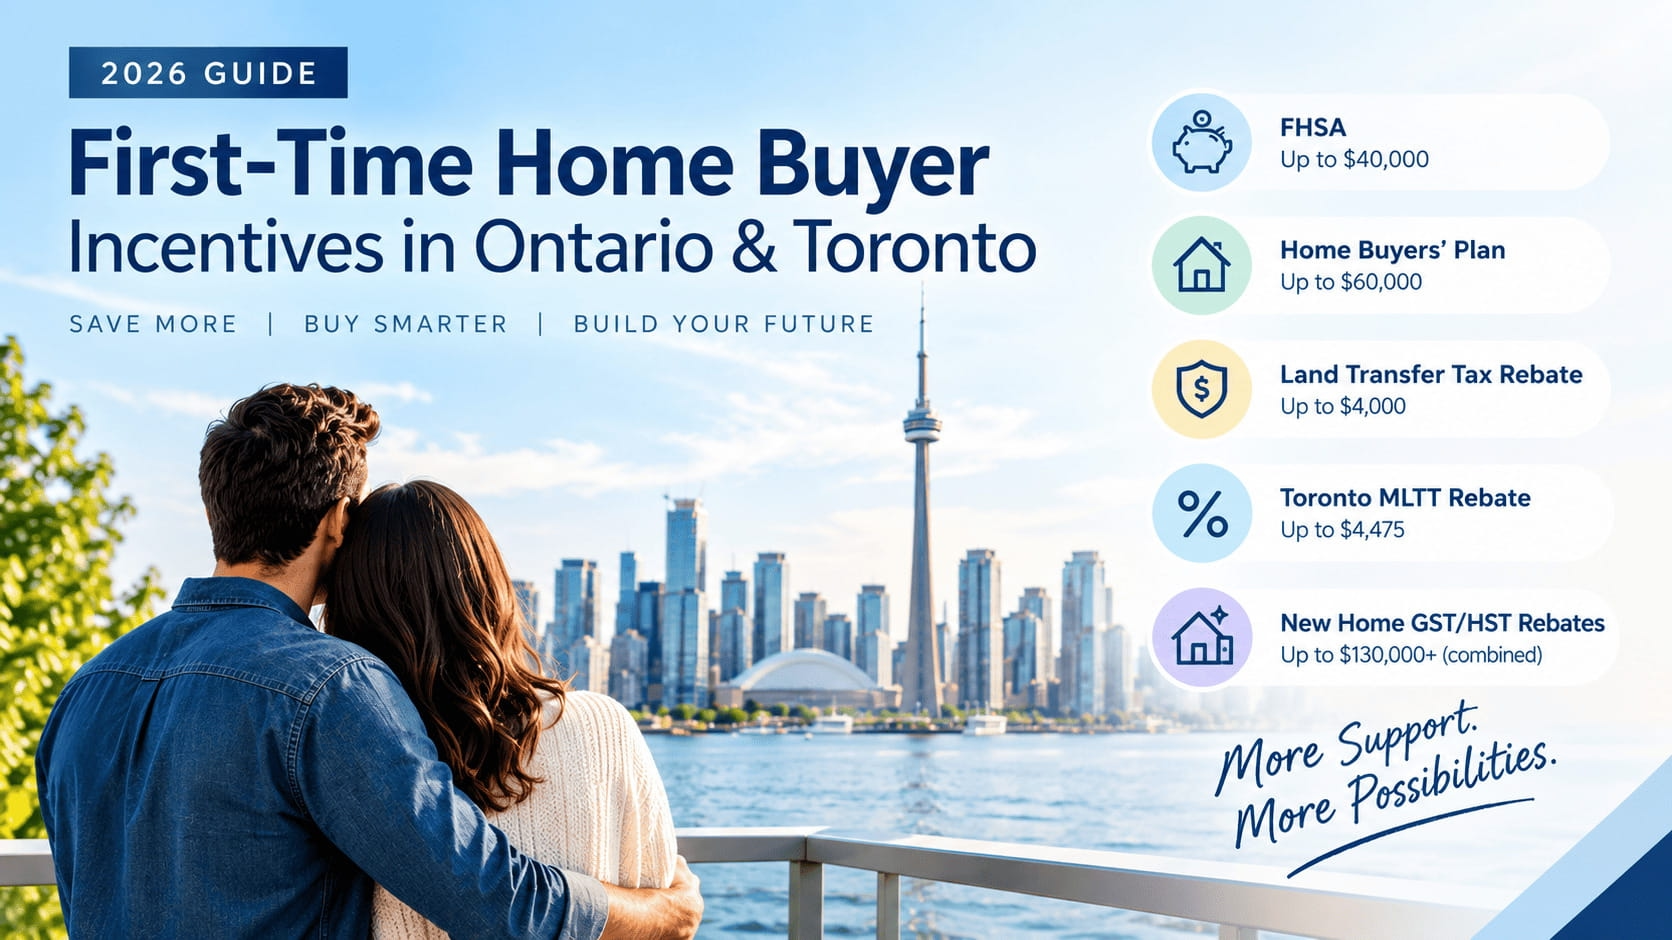
This guide explains the major 2026 first-time home buyer incentives in Ontario and Toronto, including the FHSA, Home Buyers’ Plan, land transfer tax rebates and the new GST/HST rebates for qualifying new homes.
Important: Government programs have detailed eligibility requirements and can change. This article is intended for general information and should not replace advice from your mortgage professional, accountant or lawyer.
1. First Home Savings Account (FHSA)
For many first-time buyers, the First Home Savings Account (FHSA) is one of the most valuable tools available.
An FHSA allows eligible first-time buyers to save for a home while receiving tax advantages.
How much can you contribute?
You can generally contribute:
- $8,000 per year
- Up to $40,000 over your lifetime
Contributions are generally deductible from your taxable income, and qualifying withdrawals to purchase a first home are tax-free.
One important point that many buyers don’t realize:
Your FHSA contribution room does not start accumulating until you actually open your first FHSA.
So if you are planning to buy a home in the next few years, opening an FHSA early can be valuable.
Can I transfer money from my RRSP to my FHSA?
Yes, in certain circumstances you can transfer funds from an RRSP to an FHSA, subject to the FHSA rules and contribution limits. However, an RRSP-to-FHSA transfer generally does not create another tax deduction.
My recommendation for first-time buyers
If you’re serious about buying your first home, speak with your financial institution or financial advisor about opening an FHSA before you start house hunting.
2. Home Buyers’ Plan (HBP)
The Home Buyers’ Plan (HBP) allows eligible buyers to withdraw money from their RRSP to purchase or build a qualifying home.
The current withdrawal limit is:
Up to $60,000 per person
For example, if two eligible buyers are purchasing together, each may potentially withdraw up to $60,000 from their own RRSP, subject to the program’s requirements.
The money can be used toward your home purchase without being treated as a normal taxable RRSP withdrawal, provided you meet the HBP requirements.
The amount withdrawn generally has to be repaid to your RRSP over 15 years.
Can I use the FHSA and HBP together?
Yes.
Eligible buyers can potentially use both their FHSA and RRSP through the Home Buyers’ Plan for the same home, provided they meet the requirements for both programs.
This can be a powerful strategy for buyers who have been saving through both accounts.
2026 repayment change
There is also temporary repayment relief for people making their first HBP withdrawal between January 1, 2026 and December 31, 2028.
For these buyers, the 15-year repayment period starts in the fifth year following the year of the first withdrawal, rather than the second year under the previous rule.
3. Ontario First-Time Home Buyer Land Transfer Tax Refund
Ontario provides a land transfer tax refund for eligible first-time home buyers.
The maximum Ontario refund is:
Up to $4,000
This can apply to both resale and newly constructed homes, provided the buyer meets the eligibility requirements.
Land transfer tax is calculated when you purchase a property, so this refund can reduce the amount you need to pay at closing.
Example
If your Ontario Land Transfer Tax is $6,000 and you qualify for the maximum $4,000 first-time buyer refund:
$6,000 LTT
− $4,000 rebate
= $2,000 net Ontario LTT
Your actual tax depends on the purchase price.
4. Toronto First-Time Home Buyer Land Transfer Tax Rebate
There is an additional benefit if you are purchasing a property within the City of Toronto.
Toronto has its own Municipal Land Transfer Tax (MLTT), in addition to Ontario’s provincial Land Transfer Tax.
Eligible first-time buyers may receive a:
Toronto MLTT rebate of up to $4,475
The Toronto rebate applies to qualifying residential properties, including both resale and newly constructed homes.
This means an eligible first-time buyer purchasing in Toronto could potentially receive:
Ontario LTT rebate: up to $4,000
Toronto MLTT rebate: up to $4,475
Potential combined savings:
Up to $8,475
This is one of the biggest differences between purchasing in the City of Toronto and purchasing elsewhere in the GTA.
For example, a first-time buyer purchasing in Vaughan, Markham or Richmond Hill may qualify for the Ontario rebate but would not receive Toronto’s separate municipal rebate because those municipalities do not charge Toronto’s MLTT.
5. New 2026 First-Time Home Buyer GST/HST Rebate
This is one of the most important changes for first-time buyers considering a new construction home.
The federal government introduced a new First-Time Home Buyers’ GST/HST rebate.
For eligible first-time buyers:
- New homes valued at $1 million or less can qualify for a rebate of up to 100% of the federal GST portion of HST, to a maximum of $50,000.
- For homes between $1 million and $1.5 million, the rebate is gradually reduced.
- Homes at or above $1.5 million do not qualify for the federal first-time buyer GST/HST rebate.
This is particularly important for buyers considering condos, townhomes and new construction in the GTA.
6. Ontario’s First-Time Home Buyer HST Rebate
Ontario has also introduced a major rebate for eligible first-time buyers purchasing qualifying new homes.
The Ontario first-time home buyer rebate can provide up to:
$80,000 of relief on the provincial portion of HST
For eligible new homes, the Ontario rebate follows the federal first-time buyer GST/HST rebate eligibility framework.
When the federal and Ontario measures are combined, an eligible first-time buyer purchasing a qualifying new home valued at $1 million or less could potentially receive up to:
$130,000 in combined federal and Ontario HST relief
That is potentially:
Up to $50,000 federal
+ up to $80,000 Ontario
= up to $130,000
This is a significant consideration for anyone comparing a new construction property with a resale home.
7. Ontario Enhanced New Housing Rebate — Another Important 2026 Change
Ontario’s enhanced new housing rebate is also important for buyers of qualifying new homes.
For eligible homes purchased from a builder under the applicable 2026–2027 rules, the enhanced Ontario rebate can provide relief on the provincial portion of HST.
The current rules provide:
- Homes up to $1 million: up to $80,000
- Homes between $1 million and $1.5 million: $80,000
- Homes above $1.5 million and below $1.85 million: a partial rebate
- Homes at or above $1.85 million: the enhanced rebate is not available
The program generally applies to qualifying builder purchases with agreements entered into between April 1, 2026 and March 31, 2027, subject to the detailed eligibility requirements.
What about the Ontario New Home Affordability Payment?
Eligible buyers may also qualify for the Ontario New Home Affordability Payment (ONHAP).
The payment can provide up to $50,000, but it interacts with the federal GST/HST rebates, so it should not simply be added on top of every other rebate.
The exact amount depends on the buyer’s circumstances and the applicable rebate calculations.
This is one area where I strongly recommend having your lawyer, accountant or builder’s tax specialist confirm the exact rebate treatment before relying on a specific dollar amount.
8. First-Time Home Buyers’ Tax Credit
There is also a federal Home Buyers’ Amount, which provides a non-refundable tax credit for eligible first-time buyers.
The federal credit can provide tax relief of up to approximately:
$1,500
It is important to understand that this is a tax credit, not a cheque or direct cash rebate.
It reduces federal income tax owing if you qualify.
9. What Does “First-Time Home Buyer” Actually Mean?
This is where things can become confusing.
“First-time buyer” does not always mean that you have never owned a home in your entire life.
Different programs can have different definitions and eligibility rules.
For example, under the Home Buyers’ Plan, you generally may not qualify if you lived in a home that you owned during the current calendar year or the previous four calendar years. Your spouse or common-law partner’s ownership and occupancy history can also affect eligibility.
Toronto’s municipal rebate has its own rules. For example, Toronto generally requires that the purchaser has not previously owned or had an ownership interest in a home anywhere in the world, subject to the program’s specific rules.
This is why you should not assume you are either eligible or ineligible based only on whether you’ve owned a property before.
10. How Much Money Could a First-Time Buyer Save?
Let’s look at a simplified example.
Imagine an eligible first-time buyer purchases a qualifying $900,000 resale home in Toronto.
Potential benefits could include:
Ontario Land Transfer Tax rebate: up to $4,000
Toronto MLTT rebate: up to $4,475
That’s potentially:
$8,475 in land transfer tax savings
The buyer could also have savings available through:
- FHSA tax deductions
- HBP RRSP withdrawal
- Home Buyers’ Amount
- Other applicable tax benefits
Now compare that with an eligible first-time buyer purchasing a qualifying $900,000 new construction home.
Depending on the specific transaction and eligibility, the buyer may also have access to the new federal and Ontario GST/HST relief programs.
The difference can be substantial.
However, the purchase price, type of property, builder, agreement date, occupancy date and individual buyer circumstances all matter.
11. What About the Minimum Down Payment?
Government incentives are helpful, but first-time buyers still need to understand the basic down-payment requirements.
For an eligible owner-occupied purchase, the minimum down payment is generally:
- 5% on the first $500,000
- 10% on the portion between $500,000 and $1.5 million
- 20% on the portion above $1.5 million
Mortgage insurance requirements and qualification rules may apply.
Example: $800,000 purchase
5% of first $500,000 = $25,000
10% of remaining $300,000 = $30,000
Minimum down payment = $55,000
However, having the minimum down payment does not automatically mean you will qualify for the mortgage.
Your income, credit, debts, interest rates, property taxes, condo fees and other financial obligations all affect affordability.
12. Don’t Forget the Other Closing Costs
One of the biggest mistakes I see first-time buyers make is focusing only on the down payment.
You should also budget for:
Legal fees
Your real estate lawyer will handle the legal work and registration.
Land Transfer Tax
Even with the first-time buyer rebate, you may still owe some land transfer tax depending on the purchase price.
Home inspection
For many resale homes, a professional inspection can be an important part of the buying process.
Appraisal
Depending on your mortgage and lender, an appraisal may be required.
Title insurance
Your lawyer will generally discuss title insurance and other closing requirements with you.
Adjustments
You may have to reimburse the seller for prepaid property taxes, utilities or condominium expenses.
Condo fees
If you’re buying a condominium, monthly maintenance fees need to be included in your affordability calculations.
Moving and setup costs
Don’t forget moving expenses, furniture, appliances, renovations and other initial costs.
13. First-Time Buyers Should Get Pre-Approved Before Shopping
Before you start visiting properties, I recommend getting a proper mortgage pre-approval.
A pre-approval helps you understand:
What you can technically qualify for
versus
What you should comfortably spend.
Those are not always the same number.
For example, a lender might approve you for a certain purchase price, but after considering your lifestyle, savings goals, property taxes, condo fees and other expenses, you may decide that a lower price is more comfortable.
A good first-time buyer strategy starts with the monthly payment and total ownership cost, not just the maximum purchase price.
14. Resale vs. New Construction: Which Is Better for a First-Time Buyer?
There is no universal answer.
Resale homes
Advantages can include:
- More established neighbourhoods
- More properties to choose from
- Potentially easier to compare recent sales
- You can usually see the actual home before purchasing
- Potentially lower purchase price than comparable new construction
New construction
Advantages can include:
- Newer finishes and systems
- Builder warranties
- Lower maintenance initially
- Modern layouts and energy efficiency
- Potential eligibility for significant 2026 GST/HST incentives
The new HST rebates make this comparison especially important in 2026.
A new home may qualify for significant tax relief, but buyers still need to carefully review the purchase agreement, deposit structure, occupancy provisions, closing adjustments, maintenance fees and builder reputation.
15. My Recommended First-Time Buyer Strategy
If you are planning to buy your first home in Toronto or the GTA, I would approach it in this order:
Step 1 — Determine your real budget
Don’t start with MLS listings.
Start with your income, savings, debts and monthly comfort level.
Step 2 — Speak with a mortgage professional
Get a proper pre-approval and understand the mortgage payment, property taxes, condo fees and other carrying costs.
Step 3 — Review your FHSA
If you are eligible and haven’t opened one yet, discuss opening an FHSA with your financial institution.
Step 4 — Review your RRSP
If you have RRSP savings, ask your financial advisor whether the Home Buyers’ Plan makes sense for your situation.
Step 5 — Calculate your closing costs
Don’t use every dollar of your savings for the down payment.
Keep a reserve for legal fees, land transfer tax, adjustments, moving expenses and unexpected costs.
Step 6 — Decide between resale and new construction
Don’t assume one is automatically better.
Compare the total cost of ownership, not just the advertised purchase price.
Step 7 — Understand the incentives before making an offer
Especially for new construction, the timing of the purchase agreement and the property’s value can affect your eligibility for GST/HST programs.
Step 8 — Have the right professionals review the numbers
Your Realtor, mortgage professional, lawyer and accountant each have different roles.
The best results usually come when everyone is working from the same numbers.
Frequently Asked Questions
Can first-time buyers get more than one incentive?
Yes. Depending on your situation, you may be able to combine programs such as the FHSA, Home Buyers’ Plan, land transfer tax rebates and applicable tax credits. New-home GST/HST programs may also apply to eligible purchases.
Can I use my FHSA and RRSP together?
Yes. Eligible buyers can potentially use an FHSA qualifying withdrawal and the Home Buyers’ Plan for the same purchase, subject to the requirements of each program.
How much is the Ontario first-time home buyer land transfer tax rebate?
The maximum Ontario first-time buyer refund is $4,000.
How much is the Toronto first-time home buyer rebate?
Eligible buyers can receive up to $4,475 on the Toronto Municipal Land Transfer Tax.
Can I get the Toronto rebate if I’m buying in Vaughan or Markham?
No. Toronto’s Municipal Land Transfer Tax rebate applies to properties within the City of Toronto. Buyers in Vaughan, Markham, Richmond Hill and other municipalities may still qualify for the Ontario first-time home buyer land transfer tax refund.
Can first-time buyers get GST/HST rebates on a new home?
Yes. Eligible first-time buyers purchasing qualifying new homes may be eligible for the federal GST/HST rebate and Ontario’s first-time home buyer HST rebate. The federal rebate can provide up to $50,000 and the Ontario rebate can provide up to $80,000, subject to the applicable rules.
Is the first-time buyer GST/HST rebate available on resale homes?
No. The new first-time buyer GST/HST rebate is designed for qualifying new or substantially renovated homes, not ordinary resale purchases.
Can I qualify if I owned a home before?
Possibly. It depends on the specific program and your ownership and occupancy history. Different programs have different definitions and requirements.
The Bottom Line for First-Time Buyers
Buying your first home is a major financial decision, but you don’t necessarily have to figure everything out on your own.
In 2026, first-time buyers in Ontario have several tools available, including:
FHSA — up to $40,000 lifetime contribution room
Home Buyers’ Plan — up to $60,000 from an RRSP
Ontario Land Transfer Tax rebate — up to $4,000
Toronto MLTT rebate — up to $4,475
Federal first-time buyer GST/HST rebate — up to $50,000
Ontario first-time buyer HST rebate — up to $80,000
Home Buyers’ Amount — up to approximately $1,500 in federal tax relief
For qualifying new homes, the federal and Ontario GST/HST measures can potentially provide up to $130,000 of combined HST relief on a home valued at $1 million or less, subject to all eligibility requirements.
The important thing is not simply knowing that these programs exist.
The key is understanding which ones apply to you before you buy.
Thinking About Buying Your First Home in Toronto or the GTA?
If you’re a first-time buyer considering Toronto, Vaughan, Maple, Richmond Hill, Markham or the surrounding GTA, I can help you understand the buying process, compare resale and new construction opportunities, and build a purchase strategy around your budget.
Before making an offer, I recommend having the applicable incentives and financing reviewed with your mortgage professional and lawyer so you know exactly what you qualify for.
Have questions about buying your first home? Contact me and let’s go through your situation and numbers together.